
Credit card statement converter
Convert credit card statement PDFs from any issuer into clean Excel, CSV or QuickBooks files. AI extraction reads every purchase, payment, fee and interest line, signs charges correctly, and reconciles to the Account Summary.
Excel · CSV · QBO · OFX · Xero · scanned or digital · reconciled to the summary

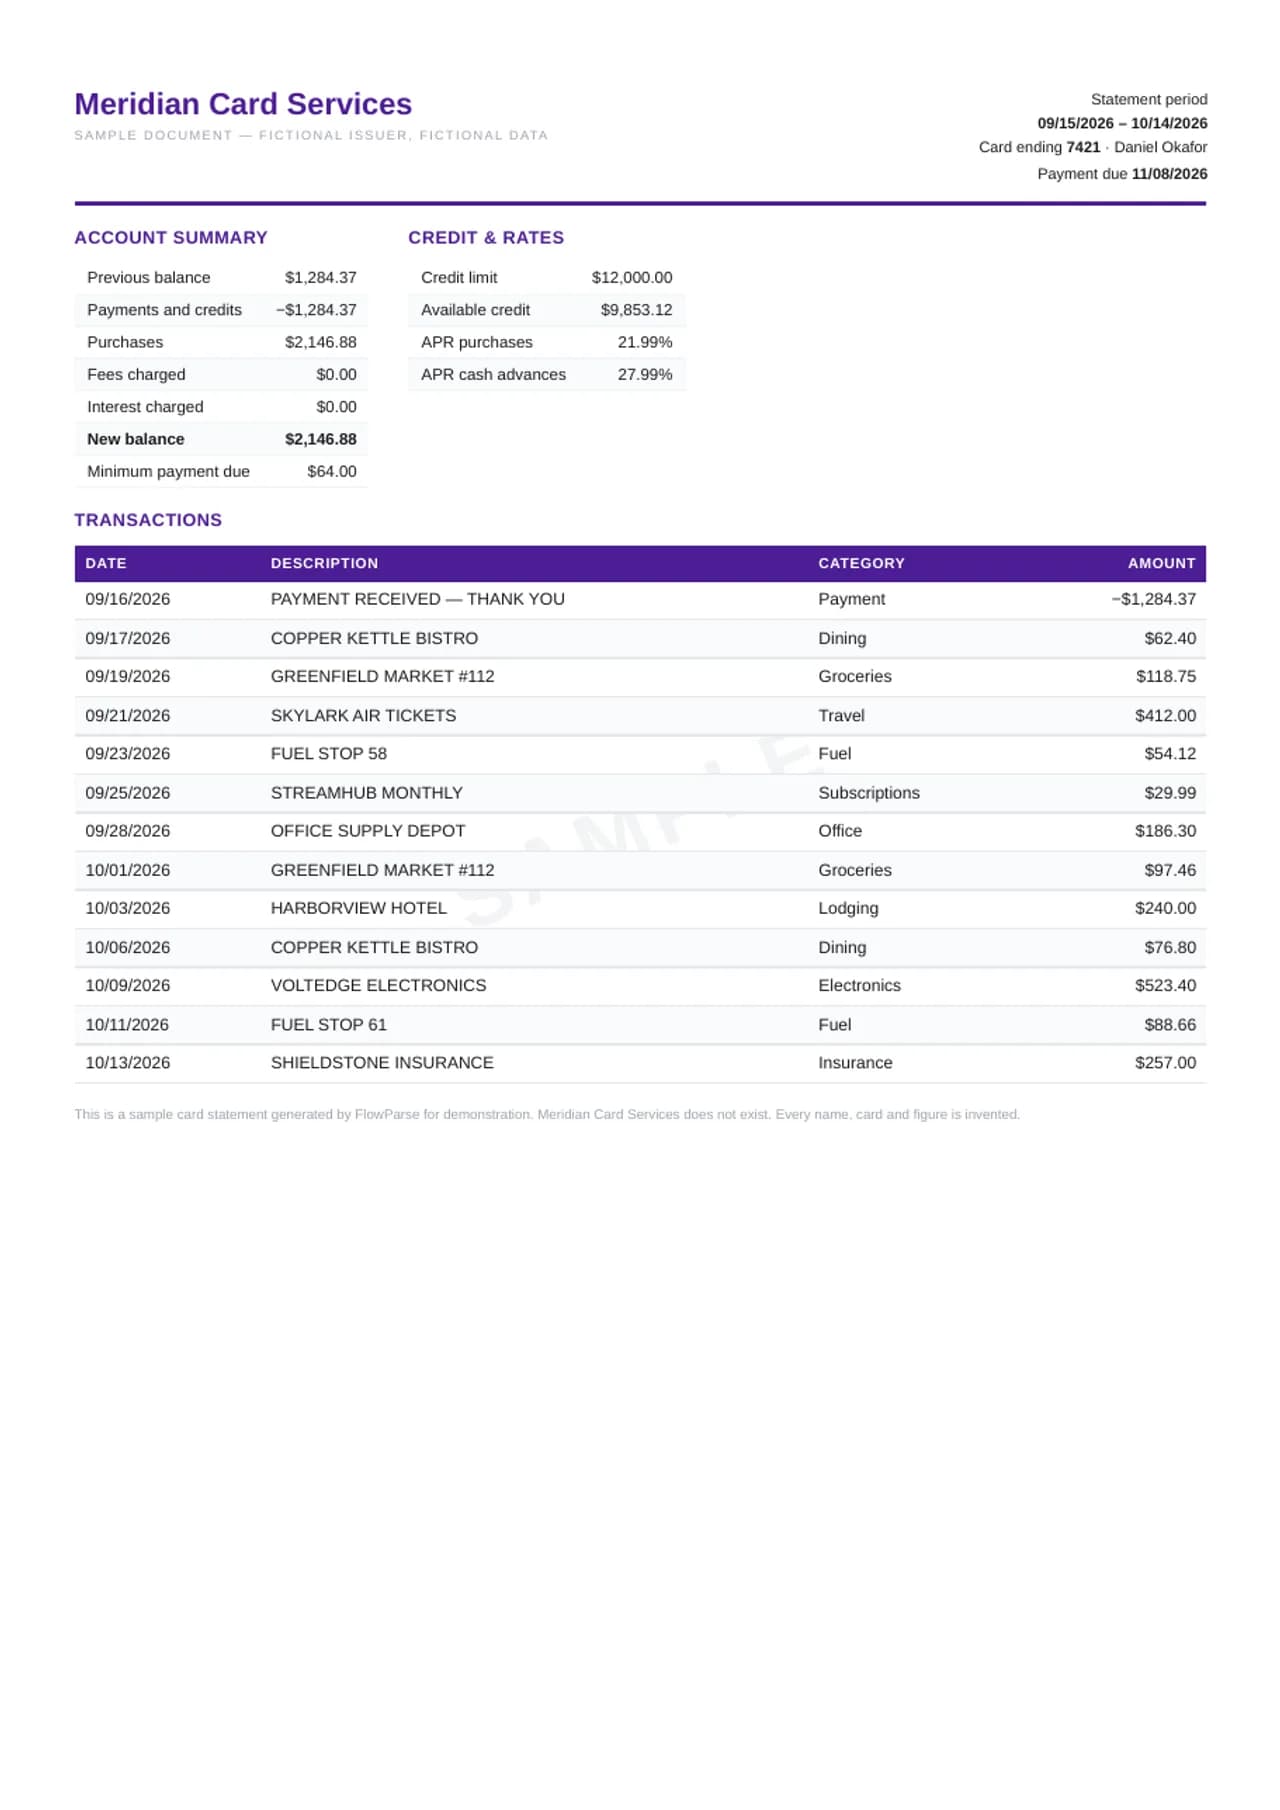
A real sample: credit card statement — to a working spreadsheet
A fictional sample document converted by the same engine you get — flip through the source PDF and every export format, or download the files themselves.
One converter for every credit card statement
Card issuers hand you a PDF. Your expense report, your accounting software and your tax prep all want structured data. A credit card statement converter closes that gap: it reads every charge and payment off the statement and rebuilds it as clean, editable rows you can categorise, total and reconcile — without retyping a single line.
Card statements are not bank statements. Instead of a running balance, they run on a billing cycle — previous balance, purchases, payments, cash advances, fees and interest, then a new balance with a minimum payment and due date. FlowParse reads that structure the way a bookkeeper would: purchases stay positive, payments and refunds go negative, fees and interest are separated from spending, and the transaction total ties back to the Account Summary.
This page is the hub for the whole workflow. Convert a single card statement to Excel, combine a year of cards with combine credit card statements, or jump straight to your issuer below. For bank accounts, see the bank statement converter.
AI extraction, no templates
Reads any issuer's layout — no per-card setup.
Merchant kept on every row
Sort and categorise spend by merchant in Excel.
Fees & interest separated
Spending, fees and finance charges in distinct columns.
Reconciles to the summary
Transaction total checked against the new balance.
Convert to the format you actually need
The same extraction powers every export, so you only convert once and choose the output that fits your next tool — a spreadsheet for an expense report, a CSV to import, or a real bank-feed file for your accounting software.
| Format | Best for |
|---|---|
| Excel (.xlsx) | Expense reports, categorising, totals by merchant |
| CSV | Importing into any tool that takes a CSV |
| .QBO | QuickBooks Online & Desktop (Web Connect) |
| .OFX | Most other accounting tools |
| Xero CSV | Xero's statement import & reconciliation |
Pick your card issuer
Dedicated converters for the major issuers, each tuned to that issuer's Account Summary and activity layout. A statement from any other issuer works exactly the same way — there are no templates to pick.
American Express
Convert statement →
Chase
Convert statement →
Capital One
Convert statement →
Citi
Convert statement →
Discover
Convert statement →
Also read, with no setup:
From PDF to clean data in three steps
1 · Upload the PDF
Drop one statement or many — digital or scanned, any issuer, any number of pages.
2 · AI extracts & checks
Every transaction is read, charges and payments signed, fees and interest separated, the total checked against the summary.
3 · Review & export
Check the editable preview, then download Excel, CSV, QBO, OFX or Xero.
Prefer a walkthrough? Read how to convert a statement PDF to Excel or how to extract transactions from a PDF.
Turn a year of card spending into one workbook
Card statements are where most business spending lives, so the usual job is an expense report. FlowParse keeps the merchant and date on every row, so categorising and totalling spend takes minutes. And with Smart Merge you can take up to 100 statements — across cards and months — into one unified sheet with duplicates removed and a source reference per row.
Import card transactions into your books
A spreadsheet is great for an expense report, but if the card activity needs to land in your books, FlowParse builds a real bank-feed file. The .QBO imports the card transactions directly into QuickBooks with no CSV column mapping, and each transaction carries a unique ID so re-imports never duplicate.
Reconciled to the Account Summary
Converting a statement is only useful if the numbers are right. FlowParse checks the converted card data the way a careful bookkeeper would, so errors surface before they reach your expense report or your books:
See how the checks work on the statement validation and reconciliation pages.
Your card statements stay private
Credit card statements expose your full spending history, so converting one should never put it at risk. FlowParse is built so it doesn't.
Encrypted transfer
Every upload and download runs over TLS.
Auto-deleted in 30 days
Your original PDF is removed automatically 30 days after upload.
EU servers
Stored on servers in the EU.
No AI training
Your documents are never used to train models. GDPR-aligned.
Read the full security overview.
Who uses a credit card statement converter
Employees & freelancers
Turn a month of card charges into a categorised expense report in minutes.
Accountants
Bring a client's card activity into the books for the period without re-keying.
Small businesses
Track and categorise card spend across employees and cards.
Budgeters
Pull a year of statements into Excel to see where the money goes.
Bookkeepers
Import card transactions straight into QuickBooks or Xero.
Anyone with a card PDF
Skip the manual typing — convert and move on with your day.
What is read from a credit card statement
A card statement has two halves. The summary box at the top tells you where the account stands; the transaction list below tells you how it got there. Both are read. The transactions come out one per row — date, description, the category where the issuer prints one, and the amount — and the summary comes out as its own block in the Excel workbook, so the figures you would otherwise copy by hand are already there.
| From the summary | Why you might need it |
|---|---|
| Previous balance, payments and credits, purchases, cash advances, fees, interest, new balance | The totals the statement is checked against |
| Minimum payment due and payment due date | Cash planning; proving payments were on time |
| Credit limit, available credit, cash advance limit | Loan and mortgage applications; credit utilisation |
| APR for purchases, cash advances and balance transfers | Comparing cards; checking a rate change |
| Rewards points earned and balance | Tracking points on a business card |
Fields are filled when the statement prints them; nothing is estimated.
The check every card statement must pass
Every issuer prints the same identity somewhere on the summary: what you owed last time, plus everything added this cycle, minus what you paid, equals what you owe now. The converted statement is checked against it, and the listed transactions are compared with the summary's totals. A missed charge, a payment read as a purchase or a lost page shows up as a statement that does not add up.
| Previous balance | 1,240.00 |
| + Purchases | 2,315.48 |
| + Cash advances | 0.00 |
| + Fees | 35.00 |
| + Interest | 18.62 |
| − Payments | 1,240.00 |
| = New balance | 2,369.10 |
Figures are an illustration.
From card statement to expense report
- 1. Convert the statement and download Excel.
- 2. Filter out what is not an expense: payments to the card, refunds you will claim separately, personal purchases on a mixed-use card.
- 3. Sort by date or category and add a column for the project, client or cost code your expense policy asks for.
- 4. Match receipts. Each row has the date, merchant description and amount a receipt needs to be matched against.
- 5. Total and submit, with the PDF statement attached as the record.
Receipts themselves convert too — see expense report to Excel.
Business cards with several cardholders
Corporate and business card statements often group charges under each employee's name. The converted rows carry the date, description, category and amount of every charge — the cardholder heading is not a separate column. If you need spending per person, use the statement the issuer produces for each card or employee where it offers one, and convert those separately; each then becomes its own file, with the card's last four digits recorded.
The account-level statement is still the one that proves the total: it is the statement checked against the summary, and the one your accounts payable team pays.
What did the card cost you this year?
Interest and fees are easy to miss when they are a line or two on each statement. Converted, they are a filter away: the summary block of each statement gives the cycle's fees charged and interest charged, and the transaction rows show each annual fee, late fee or foreign transaction fee on its own line. Add up twelve statements and you have the true cost of carrying the card for a year — a figure worth knowing before a balance transfer or a renewal.
For a business, interest and card fees are usually deductible expenses; for a household, they are the clearest number in a budget review. Either way, they are now in a column instead of scattered across twelve PDFs.
A year of card statements in one workbook
Upload twelve statements of one card together and combine them into one sheet. Each statement is checked against its own summary first. The statements are put in date order, every row carries the file it came from, and the merge review checks the chain between them: each statement's new balance should be the next statement's previous balance. A break usually means a statement is missing — worth knowing before you total a year of business expenses.
Card and bank statements together, without double counting
Each card purchase is an expense once. The monthly payment that settles the card is not a second expense — it is money moving from the bank account to the card. Put bank and card statements in the same workbook and that payment appears on both sides: as money out of checking and as a payment on the card.
In a spreadsheet, filter by source file or exclude card payments from the bank side. In accounting software or Quicken, import the card into its own credit card account — the card .QBO and .QFX are written as credit card files for exactly this reason — and record the payment as a transfer.
Things that confuse people about card statements
A charge you made is not on the statement
Pending transactions only appear once they post; a purchase in the last days of the cycle often lands on the next statement. The same goes for refunds: a return made this month may be credited on next month's statement, so look one statement ahead before you chase it.
Foreign purchases show two amounts
Issuers often print the original currency amount in the description. The amount column holds what was charged in the statement's currency — the figure that counts — and the description keeps the rest.
Purchases, payments, fees and interest are in separate sections
Many statements split them that way. They are read into one list, in statement order, so a single sort or filter works across all of them.
The statement does not add up
Usually a page did not come through or a line was misread on a scan. The preview shows the difference; open the statement, correct the row and the check passes.
Business expenses on a card, at tax time
Freelancers and small business owners often pay most business costs by card, which makes the card statements the best single record of the year's expenses. Convert all twelve, merge them, and the year's spending is in one sheet you can categorise: software, travel, equipment, advertising, meals. The interest and fees lines sit in the same sheet.
If the card mixes business and personal spending, add a column and mark each row — your tax preparer will ask for that split anyway. US sole proprietors can work from there towards Schedule C; see Schedule C from bank statements for how the categories map. Card interest on business borrowing belongs in the same review. Keep the PDF statements and the receipts behind the larger items: the converted sheet is the summary, they are the evidence.
Spotting charges you do not recognise
Reading a statement line by line is how unfamiliar charges get missed. In a spreadsheet the same review takes a minute: sort by description to see every charge from one merchant together, sort by amount to see the largest first, and look for small repeating charges — a subscription you forgot, or a test charge before a larger fraud.
A converted statement also makes it easy to compare this month's merchants with last month's: a name that has never appeared before stands out at once in a sorted list. Act quickly on anything you do not recognise. Card issuers set time limits for disputes; in the US, the Fair Credit Billing Act generally gives you 60 days from when the statement with the error was sent to report a billing error in writing. Converting each statement when it arrives keeps you well inside any window.
Is the card worth its annual fee?
The question comes up every renewal, and the answer is in the statements. Each converted statement records the rewards points earned where the issuer prints them, and the transaction rows show the annual fee and any other fees. A year merged gives you points earned, fees paid and interest charged side by side. Put a value on the points as your issuer redeems them and the comparison with the fee is one line of arithmetic. Do the same for two cards and you can see which one actually earns its place in your wallet, using a year of your own spending instead of the issuer's examples. If the fee is close to what the points are worth, the interest and late fees in the same sheet usually settle the question.
Example: a consultant's year of card spending
A management consultant puts travel, software and client lunches on one card, along with some personal shopping. In February her accountant asks for business expenses for the year. The figures here are an illustration.
She downloads the twelve statements and merges them into one workbook. Every statement passes its summary check and the review shows the chain unbroken from January to December. She adds a Business/Personal column, marks the personal rows, and filters: 412 business charges, totalled by category in a pivot table, with interest and fees listed separately. The accountant gets one file and the twelve PDFs behind it, and a job that used to take two evenings takes half an hour.
Paper and scanned card statements
Older card statements, or ones received by post, convert from a scan or a photo. They are read with OCR and then checked against the summary like any digital statement, so a misread figure shows up as a statement that does not add up rather than as a wrong expense in your report. Scan flat, one statement per file, with the summary page included — it is what the check needs.
Which file to download for a card statement
| Download | Best for |
|---|---|
| Excel | Expense reports, budgets, the year-end review — with the statement summary alongside the transactions |
| CSV | Any spreadsheet, budgeting app or script |
| .QBO | QuickBooks — written as a credit card account file |
| .QFX | Quicken — written as a credit card account file |
| .OFX | Other programs that import OFX |
| Xero, Sage and other import CSVs | Accounting software that takes a bank-statement CSV |
All of them are included on every plan. For QuickBooks specifically, see the PDF to QBO converter.
Every issuer lays it out differently
The identity behind every card statement is the same, but the layout is not. Some issuers list payments and purchases together by date; others split them into sections. Some print a category for every charge; most do not. Some put the summary on the first page, others at the end. Because the converter reads the statement rather than a template, the layout does not need to be known in advance.
What does differ by issuer is where you find the statements and what else the issuer lets you download. Our issuer pages cover that for American Express, Chase, Capital One, Citi and Discover, with details checked on each issuer's own site.
A household budget from card statements
For many households the credit card, not the bank account, is where day-to-day spending happens: groceries, fuel, subscriptions, eating out. The bank statement then shows one large card payment a month and hides everything that matters for a budget inside it. The card statement is where the detail lives.
Convert three months of card statements and the picture is usually clear: sort by description to find every subscription, total by category where the issuer prints one or add your own, and compare month against month. Our guide to categorising transactions suggests a simple set of categories to start with. Because each statement is checked against its own summary, the totals you build match what the issuer billed — the budget starts from real numbers, not an estimate. Repeat it each quarter and the trend is there too.
In short
Upload a card statement from any issuer — digital, scanned or photographed. Every charge, payment, fee and interest line comes out as a row with its date, description, category where printed and amount, and the summary comes out with it. Before you download, the statement is checked: previous balance plus purchases, cash advances, fees and interest, minus payments, must equal the new balance.
Download Excel for reports and reviews, or a credit card .QBO, .QFX or import CSV for your books — every format on every plan, with ten free pages a month to start.